





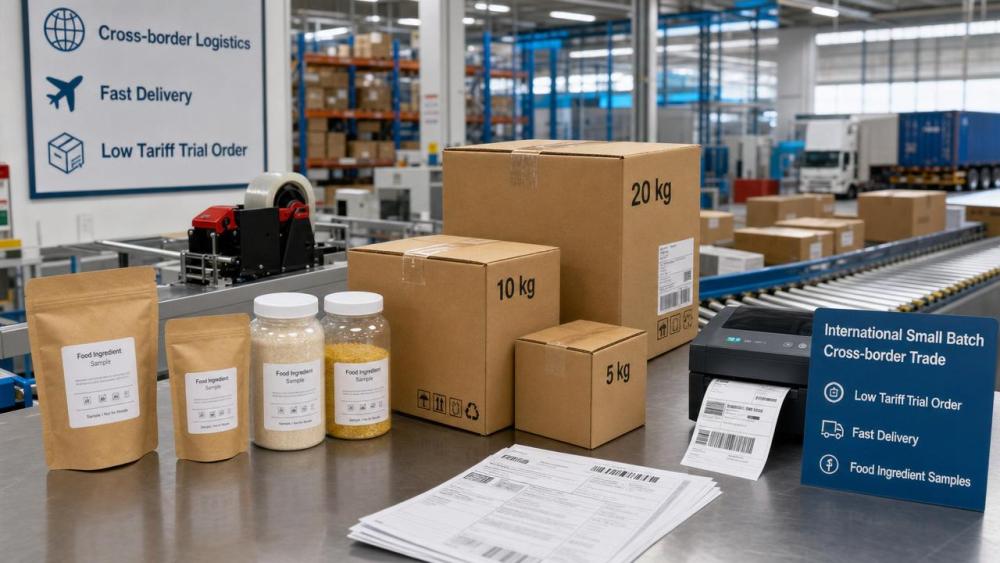
On May 11, 2026, Brazil’s Federal Revenue Service (RFB) removed IPI and II on imported goods valued at US$50 or less per shipment, a change that directly affects small sample and trial orders in categories such as water-soluble flavors, natural antioxidants, and food preservatives. For distributors in South America, the immediate point of attention is not only lower tax friction on low-value imports, but also a visible rise in 5–20 kg purchasing activity and a shorter 7–10 day delivery window, which matters to suppliers, buyers, and channel partners involved in fast product validation.
What has been confirmed since May 11
According to the information provided, the policy took effect on May 11, 2026. Brazil’s Federal Revenue Service canceled the IPI and II applicable to imported goods with a declared value of no more than US$50 per shipment.
The scope described in the event summary includes small-format samples and trial orders for water-soluble flavors, natural antioxidants, and food preservatives. The same summary also indicates that South American distributors are concentrating purchases in 5–20 kg lots, while delivery cycles have been compressed to 7–10 days.
The confirmed business relevance in the input is that this setup supports faster validation of active flavor and preservation solutions from Chinese suppliers.
Why the change matters across the supply chain
Small-lot cross-border trade becomes more practical
From an industry perspective, direct trading companies and export-oriented suppliers may be affected first because the policy applies at the shipment level for low-value imports. Where orders are sample-based or intended for early-stage testing, the removal of IPI and II can reduce friction in the initial transaction step. What deserves closer attention is whether more customer conversations now move from quotation to test order faster than before.
Distributors gain speed in product screening
For distributors and channel operators in South America, the reported increase in 5–20 kg purchasing suggests a more active sample-selection phase. The impact is likely to be felt in SKU evaluation, pilot introductions, and the pace of supplier comparison. In practice, these companies will need to watch whether the shorter 7–10 day delivery expectation becomes a new baseline for trial-stage cooperation.
Ingredient buyers and application teams may test more frequently
Procurement teams and downstream application users in flavor and preservation-related segments may also feel the effect, especially when product decisions depend on repeated sampling rather than immediate bulk purchase. Analysis shows that the tax change could make low-volume verification easier to initiate, but the operational value will still depend on whether shipments, specifications, and sample documentation align with customer testing needs.
Supply chain service providers face a tighter execution window
Service providers involved in export handling, documentation, and delivery coordination may see pressure shift from cost discussion to execution reliability. Observably, when trial orders increase and delivery cycles shorten, fulfillment accuracy becomes more visible than before. The key issue is not just moving small parcels, but doing so in a way that supports quick technical and commercial feedback.
What companies should watch now
Track how the rule is expressed and applied in practice
Companies should pay close attention to any subsequent official wording or implementation details related to the sub-US$50 threshold. The policy signal is clear in the event summary, but businesses still need to distinguish between a stated tax removal and day-to-day operational handling in real transactions.
Align sample design with the 5–20 kg order pattern
The purchasing pattern described in the input points to a practical change in trial behavior. Suppliers and trading teams should focus on whether their sample packs, minimum dispatch units, and internal response process fit 5–20 kg requests rather than larger conventional export lots.
Prepare for shorter delivery expectations
With delivery cycles reportedly narrowing to 7–10 days, lead-time management becomes a frontline issue. This is less about broad capacity expansion and more about whether documentation, shipment release, and customer communication can support faster trial conversion without avoidable delays.
Keep qualification and product files ready for validation-stage demand
For products such as water-soluble flavors, natural antioxidants, and food preservatives, small-batch buyers are often testing fit rather than committing to scale. That makes specification clarity, shipment consistency, and basic supporting documents especially important in the early stage of engagement.
How this should be read at this stage
Analysis shows that this development is best understood as a near-term facilitation signal for sample and trial-order activity rather than as proof of a broader structural shift in trade volumes. The immediate evidence in the input points to stronger small-lot purchasing behavior and faster delivery expectations, which is meaningful for validation workflows.
At the same time, it is more appropriate to understand this as an operationally important market signal that still requires observation. The reason is simple: the current confirmed facts relate to tax removal on low-value shipments, category coverage for certain ingredient samples, an increase in 5–20 kg orders, and a 7–10 day delivery cycle. Broader conclusions beyond that would need further verification.
A practical signal for faster market testing
For the ingredients and solutions mentioned in the event summary, the policy change matters because it lowers the barrier to trying products before scaling them. The strongest current takeaway is not that the market has been fully reshaped, but that early-stage commercial testing between suppliers and South American buyers may now move faster and with less tax friction on small shipments.
In that sense, the update is better read as a concrete short-term business enabler with possible wider implications if the trial-order pattern continues. For now, a measured interpretation remains the most appropriate one.
Basis of this article and what still needs verification
This article is based on the user-provided news title, event date, and event summary. The summary states that from May 11, 2026, Brazil’s Federal Revenue Service removed IPI and II on imported goods valued at US$50 or less per shipment, affecting sample and trial orders for water-soluble flavors, natural antioxidants, and food preservatives, while South American distributors increased 5–20 kg purchases and delivery cycles shortened to 7–10 days.
For this type of industry update, relevant source categories typically include official government announcements, company disclosures, industry association releases, authoritative media coverage, and related trade or standards documentation. A specific official source link was not provided in the input, so continued verification is still necessary. Follow-up attention should focus on any further official clarification, implementation details, and whether the reported trial-order pattern remains sustained over time.
Related News
- When heat stable flavor formulations are needed for UHT beveragesOct 04, 2026Aromatics & Perfumery Fellow
- How heat stable flavor formulations prevent aroma loss in baked goodsOct 03, 2026Aromatics & Perfumery Fellow
- Using 4-vinyl guaiacol flavour standard to calibrate sensory panelsOct 02, 2026Aromatics & Perfumery Fellow
- Garlic Powder Flavor Profiles and Their Role in Seasoning BlendsSep 28, 2026Aromatics & Perfumery Fellow
Related News
- 00
0000-00
How to assess color stability from a natural food colors manufacturer - 00
0000-00
When does amino acid surfactant powder improve cleanser mildness? - 00
0000-00
How to verify a cosmetic nanotechnology supplier's safety documentation - 00
0000-00
How rheological thickeners for shampoo affect suspension stability - 00
0000-00
How to assess recombinant collagen ingredients for cream stability
Aromatics & Perfumery Fellow
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.